
For Raytheon employees approaching retirement, choosing Medicare coverage is an important decision that deserves careful planning. After years of receiving health insurance through an employer, transitioning to Medicare can introduce unfamiliar choices, different costs, and new considerations about access to healthcare.
One of the biggest decisions is whether to enroll in Original Medicare or Medicare Advantage.
Both provide Medicare coverage, but they work differently. Original Medicare generally offers greater flexibility in choosing doctors and hospitals, while Medicare Advantage may provide lower monthly premiums and additional benefits. Neither option is automatically better.
For Raytheon employees, there is another important consideration: how Medicare fits with any retiree medical benefits available through RTX or a legacy Raytheon benefits program.
Understanding these choices before leaving employment can help you avoid coverage gaps, unexpected expenses, and decisions that may be difficult to reverse.
Understanding Your Medicare Options
When you become eligible for Medicare, generally at age 65, you have two primary ways to receive your healthcare coverage.
Original Medicare
Original Medicare is administered by the federal government and consists of:
Part A: Hospital insurance, including inpatient hospital care and certain other services.
Part B: Medical insurance, covering physician services, outpatient care, and other medically necessary services.
Part D: Optional prescription drug coverage purchased through a separate private insurance plan.
Medigap: Optional Medicare Supplement Insurance that helps pay certain deductibles, coinsurance, and other out-of-pocket expenses.
Original Medicare generally allows you to visit any doctor or hospital in the United States that accepts Medicare.
Medicare Advantage
Medicare Advantage, also called Part C, is an alternative way to receive Medicare benefits through a private insurance company approved by Medicare.
Medicare Advantage plans provide Part A and Part B benefits, usually include prescription drug coverage, and may offer additional benefits such as dental, vision, and hearing services.
However, many plans operate through provider networks and may require prior authorization for certain medical services.
Medicare Advantage is not supplemental insurance. It replaces Original Medicare as the way you receive your Medicare-covered healthcare services.
The official Medicare coverage comparison provides additional details.
Before Choosing Medicare, Review Your Raytheon Retirement Benefits
For Raytheon employees, Medicare planning should begin with understanding what happens to your employer-sponsored health coverage when you retire.
RTX and its predecessor companies have offered different benefit arrangements over time. Depending on your employment history, legacy organization, retirement eligibility, and applicable plan documents, you may have access to retiree medical benefits or other healthcare-related resources.
Not every Raytheon employee has the same benefits.
Some employees may have access to retiree medical coverage, while others may need to obtain their own coverage after leaving employment. Certain arrangements may provide access to group Medicare plans, supplemental coverage, or other forms of assistance.
Before making a Medicare decision, review your individual benefit documents and confirm the following with the appropriate RTX benefits administrator:
Whether you are eligible for retiree medical benefits.
Whether those benefits change when you become eligible for Medicare.
Whether you must enroll in Medicare Parts A and B to maintain retiree coverage.
Whether your available retiree medical coverage is designed to coordinate with Original Medicare or Medicare Advantage.
Whether prescription drug coverage is included and considered creditable.
Whether declining or terminating retiree coverage could permanently affect your ability to enroll again.
Whether coverage or benefits are available for your spouse.
These details can materially change which Medicare option makes the most sense.
For example, an employee with access to employer-sponsored supplemental coverage may have different considerations than someone who needs to purchase an individual Medigap policy.
Medicare also cautions that joining a separate Medicare Advantage plan can sometimes affect employer or retiree coverage, including coverage for family members.
Do not assume that you can freely switch between an employer-sponsored retiree plan and an individually purchased Medicare plan without consequences.
Original Medicare: Advantages and Disadvantages for Raytheon Retirees
Original Medicare is often appealing to people who value flexibility, particularly those who travel frequently or want broad access to medical specialists.
Advantages of Original Medicare
Greater freedom to choose healthcare providers
With Original Medicare, you can generally receive covered care from any doctor or hospital in the United States that accepts Medicare.
You are not restricted to a particular insurance company's provider network, and you generally do not need referrals to see specialists.
This can be especially valuable for Raytheon employees who plan to relocate after retirement, maintain homes in different states, or travel extensively.
Someone retiring from a Raytheon location in Massachusetts, Arizona, Texas, or another state may eventually move closer to family or spend part of the year elsewhere. Original Medicare can make receiving care in multiple locations more straightforward.
Fewer prior authorization requirements
Original Medicare generally does not require prior authorization for most covered medical services.
This can simplify access to care, particularly when treatment involves multiple physicians or specialists.
The option to purchase Medigap coverage
Original Medicare allows you to purchase a Medigap policy to help cover certain out-of-pocket expenses.
For example, after you meet the Part B deductible, Original Medicare generally pays 80% of the Medicare-approved amount for covered Part B services, leaving you responsible for the remaining 20%.
Depending on the Medigap plan you choose, supplemental insurance may cover much of that remaining expense.
For someone who prefers greater predictability in healthcare costs, Original Medicare combined with Medigap may be attractive.
However, employees eligible for Raytheon-related retiree medical benefits should first determine whether those benefits already provide supplemental coverage or have specific coordination requirements.
Disadvantages of Original Medicare
Potentially higher monthly premiums
Original Medicare combined with Medigap and a separate Part D prescription drug plan may involve multiple monthly premiums.
You will generally pay the Part B premium, a Medigap premium, and potentially a Part D premium.
Although supplemental coverage can reduce expenses when you receive medical care, the recurring premiums may be higher than those of some Medicare Advantage plans.
No annual out-of-pocket maximum without supplemental coverage
Original Medicare alone does not have an annual limit on out-of-pocket costs for covered Part A and Part B services.
Without Medigap or another source of supplemental coverage, a significant medical event could result in substantial expenses.
Limited coverage for certain services
Original Medicare generally does not cover routine dental care, routine eye exams, hearing aids, or most long-term custodial care.
These expenses may require separate insurance or additional retirement savings.
More coverage decisions to coordinate
You may need to select and maintain separate policies for prescription drugs and supplemental coverage.
For someone accustomed to an employer-sponsored health plan, this can require more involvement in managing healthcare coverage.
Medicare Advantage: Advantages and Disadvantages for Raytheon Retirees
Medicare Advantage plans can be appealing because they combine multiple types of coverage into one plan, often with lower monthly premiums.
However, the tradeoffs may involve restrictions on healthcare providers and additional requirements for receiving certain services.
Advantages of Medicare Advantage
Potentially lower monthly premiums
Some Medicare Advantage plans have a $0 additional monthly plan premium.
You generally must still pay your Medicare Part B premium, but the absence of an additional plan premium may make Medicare Advantage less expensive on a monthly basis than Original Medicare combined with Medigap and Part D.
However, lower premiums do not necessarily mean lower total healthcare costs.
Prescription drug coverage is often included
Most Medicare Advantage plans include Part D prescription drug coverage.
This can simplify how you manage your healthcare benefits because you generally do not need a separate prescription drug plan.
Additional benefits
Many Medicare Advantage plans offer benefits that Original Medicare generally does not cover, such as certain dental, vision, and hearing services.
Some plans may also include fitness programs or other supplemental benefits.
However, the scope of these benefits varies considerably. Dental coverage, for example, may be subject to annual limits, restricted provider networks, or exclusions for certain procedures.
An annual out-of-pocket maximum
Medicare Advantage plans have an annual limit on what you pay out of pocket for covered Medicare Part A and Part B services.
Once you reach the applicable limit, the plan generally pays the full cost of covered services for the remainder of the year.
This provides a measure of financial protection that Original Medicare does not offer without supplemental coverage.
However, the maximum can still be substantial. Premiums, prescription drug costs, and noncovered services generally do not count toward that medical out-of-pocket limit.
Disadvantages of Medicare Advantage
Provider network restrictions
Many Medicare Advantage plans operate through Health Maintenance Organization (HMO) or Preferred Provider Organization (PPO) networks.
An HMO generally requires you to receive nonemergency care from providers within its network, subject to certain exceptions. A PPO may allow out-of-network care, but usually at a higher cost.
This can be particularly important for Raytheon employees who expect to move after retirement or spend extended periods in different states.
A plan that works well near your current home may not provide the same access to physicians and hospitals in another location.
Prior authorization requirements
Medicare Advantage plans may require approval before covering certain medical services, procedures, or supplies.
These requirements can create additional administrative steps and, in some circumstances, delays or disputes over coverage.
Although Medicare Advantage plans must cover medically necessary services that Original Medicare covers, the process for accessing those services can differ.
Costs can increase with healthcare usage
Lower monthly premiums may be offset by copayments, coinsurance, and other expenses when you receive care.
If you require frequent specialist visits, outpatient treatments, or hospital services, your total annual costs may be considerably higher than the monthly premium initially suggests.
Benefits and networks can change
Medicare Advantage plans can change their premiums, provider networks, prescription drug formularies, and supplemental benefits from year to year.
A plan that works well today may be less attractive in the future.
This makes it important to review your coverage annually rather than assuming your current plan will remain appropriate indefinitely.
Original Medicare vs. Medicare Advantage: A Side-by-Side Comparison
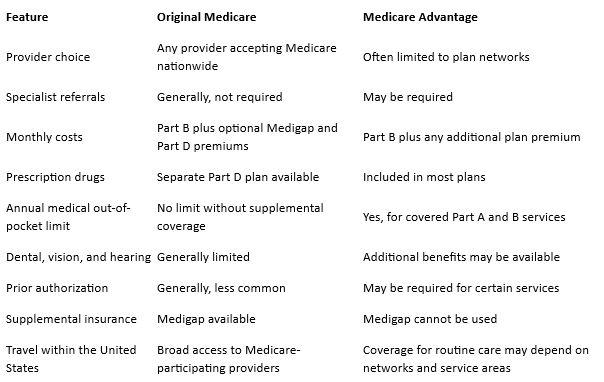
For Raytheon employees, the comparison should also include any employer-sponsored retiree coverage available to you. That coverage may affect both the costs and the options you can choose.
One Important Consideration: Switching Plans Later May Not Be Easy
One of the most overlooked aspects of this decision is the potential difficulty of moving from Medicare Advantage to Original Medicare with supplemental coverage later.
You can generally switch between Original Medicare and Medicare Advantage during Medicare's annual Open Enrollment Period, October 15 through December 7.
However, switching back to Original Medicare does not necessarily mean you will be able to purchase a Medigap policy on the same terms available when you first became eligible.
Under federal rules, your initial Medigap Open Enrollment Period generally lasts six months, beginning the first month you are both age 65 or older and enrolled in Medicare Part B.
During this period, insurance companies generally cannot deny you a Medigap policy because of preexisting health conditions.
After that window closes, insurers may be permitted to evaluate your medical history, charge higher premiums, or deny coverage altogether.
Certain guaranteed-issue protections, including limited trial rights, and state-specific rules provide exceptions, but they do not apply in every situation.
Consider a Raytheon employee who retires at age 65 and selects Medicare Advantage because of its lower premiums.
Several years later, that person develops a medical condition requiring treatment from specialists outside the plan's network.
Original Medicare may now appear more attractive because of its broader provider access.
Although returning to Original Medicare may be possible, obtaining affordable Medigap coverage could be more difficult.
This is why the initial decision deserves careful consideration.
You can learn more through Medicare's Medigap enrollment guidance.
Medicare Enrollment Timing Matters When Leaving Raytheon
For employees retiring around age 65 or continuing to work beyond that age, the timing of Medicare enrollment is another important consideration.
If you are covered by a qualifying employer group health plan based on current employment, you may be able to delay Medicare Part B enrollment without incurring a late enrollment penalty.
However, retiree coverage and COBRA generally do not provide the same protection as active-employment coverage for delaying Part B.
When qualifying active-employment coverage ends, a special enrollment period may allow you to enroll in Part B without waiting for the general enrollment period.
The timing matters because a mistake could create a coverage gap or late enrollment penalties.
Employees who continue working after age 65 should also consider how Medicare enrollment interacts with Health Savings Account (HSA) contributions.
Once you are enrolled in Medicare, you generally cannot make or receive HSA contributions for the months you are covered. Retroactive Medicare Part A enrollment can create additional complications.
Before leaving Raytheon, confirm the end date of your active employee health coverage, the effective date of any retiree medical benefits, and the Medicare enrollment deadlines that apply to you.
The Medicare enrollment guidance provides information about enrollment periods and eligibility.
How Medicare Choices Affect Your Raytheon Retirement Financial Plan
Healthcare costs are an important part of retirement planning, and the decision between Original Medicare and Medicare Advantage extends beyond comparing insurance premiums.
For Raytheon employees, the decision may also interact with pension benefits, 401(k) withdrawals, investment income, and the timing of retirement.
Depending on your employment history and applicable benefit plans, you may have a pension, defined contribution accounts, or other retirement resources.
These income sources should be coordinated with your anticipated healthcare expenses.
Medicare Premiums and IRMAA
Medicare Part B and Part D premiums can increase when your income exceeds certain thresholds.
These adjustments, known as Income-Related Monthly Adjustment Amounts (IRMAA), can apply whether you choose Original Medicare or Medicare Advantage.
Medicare generally uses income information from your federal tax return from two years earlier to determine whether IRMAA applies.
For a Raytheon employee transitioning into retirement, that can create an important timing issue.
Your Medicare premiums may initially reflect income earned while you were still working, even though your income has declined after retirement.
A qualifying life-changing event, including work stoppage or work reduction, may allow you to request a new IRMAA determination using more recent income information.
Roth conversions, capital gains, and certain other financial decisions can also affect Medicare premiums.
We discuss the process in more detail in How to Appeal IRMAA: A Step-by-Step Guide to Lowering Medicare Premiums.
Healthcare Costs and Retirement Income
Healthcare spending should be evaluated alongside your retirement income strategy.
Someone who chooses Original Medicare with Medigap may have higher recurring premiums but more predictable expenses for many covered services.
Someone who chooses Medicare Advantage may have lower monthly premiums but greater variability in expenses when receiving care.
Neither approach is inherently better.
What matters is understanding how each option fits your healthcare needs, lifestyle, and financial resources.
As we discuss in Retirement Planning Beyond the 4% Rule, retirement income planning requires more than selecting a withdrawal percentage. Taxes, spending patterns, investment returns, and changing circumstances all influence the sustainability of a retirement plan.
Healthcare decisions are an important part of that analysis.
Which Medicare Option Is Right for You?
When comparing Original Medicare and Medicare Advantage, Raytheon employees should consider several practical questions:
Are you eligible for retiree medical coverage through RTX or a legacy Raytheon benefits program?
How does that coverage coordinate with Medicare?
Would choosing an individual Medicare Advantage plan affect your retiree benefits?
How important is it to see doctors and specialists without network restrictions?
Do you plan to relocate or spend extended periods away from your primary residence?
Would you prefer higher, more predictable monthly premiums or potentially lower premiums with variable healthcare expenses?
What prescription medications do you take, and how are they covered under the available plans?
How might your healthcare needs change over the next 10 or 20 years?
If you choose Medicare Advantage now, would you be comfortable with the possibility that Medigap coverage could be more difficult to obtain later?
It is important to compare the actual plans available where you live rather than relying solely on general descriptions of the two Medicare options.
The Medicare Plan Finder can help you review coverage choices, estimated costs, and available benefits.
Making Medicare Part of Your Raytheon Retirement Plan
Choosing Medicare coverage is about more than finding the lowest premium. It is about understanding the tradeoffs between cost, flexibility, access to care, and financial predictability.
For Raytheon employees, it is also about coordinating healthcare coverage with the transition away from employer-sponsored benefits.
Original Medicare may appeal to people who value broad provider access and the option to purchase supplemental coverage. Medicare Advantage may appeal to those who prefer an integrated plan with potentially lower monthly premiums and additional benefits.
The right decision depends on your circumstances, including any retiree medical benefits available to you.
At Stordahl Capital Management, we have experience helping Raytheon employees navigate retirement decisions, including how employer benefits, retirement income, taxes, and healthcare costs fit together.
We believe these decisions should be evaluated as part of a comprehensive financial plan, with attention to both the financial considerations and the lifestyle you want to enjoy in retirement.
If you are approaching retirement from Raytheon and would like to discuss how Medicare and healthcare costs fit into your broader retirement plan, we invite you to schedule a complimentary 15-minute call.
Frequently Asked Questions
Do Raytheon employees receive retiree medical benefits?
Eligibility varies depending on the applicable RTX or legacy Raytheon benefits program, employment history, retirement eligibility, and plan provisions. Employees should review their individual benefits documentation and confirm their options with the appropriate benefits administrator before retiring.
Should I enroll in Medicare at age 65 if I am still working at Raytheon?
Not necessarily. If you have qualifying employer-sponsored health coverage based on current employment, you may be able to delay Part B enrollment without a late enrollment penalty. However, the rules depend on your circumstances, and Medicare enrollment can also affect HSA contributions.
Is Original Medicare better than Medicare Advantage for Raytheon retirees?
Neither option is universally better. Original Medicare generally provides greater flexibility in choosing healthcare providers, while Medicare Advantage may offer lower monthly premiums and additional benefits. Any Raytheon-related retiree medical coverage should also be considered.
Can I keep Raytheon retiree medical coverage and enroll in Medicare Advantage?
That depends on the specific retiree medical arrangement. Some employer-sponsored plans coordinate with Medicare, while others may impose restrictions or offer their own Medicare Advantage options. Confirm the rules before enrolling in an individual Medicare Advantage plan.
Can I switch from Medicare Advantage to Original Medicare later?
Yes, during applicable enrollment periods. However, obtaining a Medigap policy after switching may be more difficult if you are outside your initial Medigap Open Enrollment Period and do not qualify for guaranteed-issue protections. State rules may provide additional rights.
Can retirement from Raytheon reduce my Medicare IRMAA premiums?
Potentially. If your income decreases because you stop working or reduce your work hours, you may qualify to request a new IRMAA determination based on a qualifying life-changing event. Eligibility depends on your circumstances and the Social Security Administration's rules.
A Weekly Perspective on Planning and Markets
Each week, we share The Week in Review — a short collection of articles on
financial planning and wealth management, along with a brief overview for context.
One email per week. No promotions, no sales – just clarity.
This material was written in collaboration with artificial intelligence (ChatGPT) and derived from sources believed to be correct.
Stordahl Capital Management, Inc is a Registered Investment Adviser. This commentary is solely for informational purposes and reflects the personal opinions, viewpoints, and analyses of Stordahl Capital Management, Inc. and should not be regarded as a description of advisory services or performance returns of any SCM Clients. The views reflected in the commentary are subject to change at any time without notice. Nothing in this piece constitutes investment advice, performance data or any recommendation that any particular security, portfolio of securities, transaction or investment strategy is suitable for any specific person. Any mention of a particular security and related performance data is not a recommendation to buy or sell that security. Advisory services are only offered to clients or prospective clients where Stordahl Capital Management and its representatives are properly licensed or exempt from licensure. No advice may be rendered by Stordahl Capital Management unless a client service agreement is in place. Stordahl Capital Management, Inc provides links for your convenience to websites produced by other providers or industry-related material. Accessing websites through links directs you away from our website. Stordahl Capital Management is not responsible for errors or omissions in the material on third-party websites and does not necessarily approve of or endorse the information provided. Users who gain access to third-party websites may be subject to the copyright and other restrictions on use imposed by those providers and assume responsibility and risk from the use of those websites. Please note that trading instructions through email, fax, or voicemail will not be taken. Your identity and timely retrieval of instructions cannot be guaranteed. Stordahl Capital Management, Inc. manages its clients’ accounts using a variety of investment techniques and strategies, which are not necessarily discussed in the commentary. Investments in securities involve the risk of loss. Past performance is no guarantee of future results.
Stordahl Capital Management is an independent registered investment adviser and is not affiliated with, endorsed by, or sponsored by Raytheon, RTX Corporation, or any of their affiliates.